September 2026: Market Report

Lower harvest yields and rising energy and transport costs are adding to expectations of higher inflation, making it increasingly important for businesses to get the most from their existing spend.
Key Food & Beverage Movements
Farmers are emerging from the hottest summer on record; the UK recorded a mean temperature of 16.5°C, 1.9°C above the 1991–2020 average, while summer rainfall was only 77% of average. These conditions contributed to a disappointing and highly variable cereal and oil seed harvest, with several crops finishing well below their five-year averages:
- Winter wheat: 6.9 t/ha — 11% below average.
- Spring barley: 4.8 t/ha — 17% below average.
- Oats: 4.6 t/ha — 14% below average.
- Winter barley: 6.9 t/ha — broadly in line with average.
- Winter oilseed rape: 4.0 t/ha — 19% above average.
Fresh produce has faced similar weather-related disruption. Onion yields are around 25% below normal, with smaller bulbs expected throughout the year. Water shortages have reduced larger potato grades, particularly baker 40s and 50s, while earlier shortages have forced some lettuce crops to be harvested before reaching full weight and specification.
Speaking to the BBC about the problems this year's weather has caused her, Christine Hellio of Manor Farm said: “I've never had to irrigate pumpkins to this extreme before. We'll still have pumpkins... but everything that we have grown this year has had to be irrigated a number of times over."
It has “been an incredibly challenging year for dairy farmers too”, says Michael Bray of the Guernsey Farmers Association. According to recent AHDB data, UK milk production fell 3.5% year-on-year in August, reducing butterfat and protein volumes by 1.9% and 2.7%, respectively. UK and European wholesale markets and spot milk prices have since moved upwards, supporting farmgate prices as the market responds to lower supply.
Overarching Market Pressures
Food and non-alcoholic drink inflation remained at 1.3% in August, but the Food and Drink Federation (FDF) expects this period of relatively low inflation to be short-lived.
“Food manufacturers have worked hard to absorb the initial shock of the Iran war and protect consumers from price rises. However, after six years of turbulence and disruption, they can’t continue to absorb such a wide range of price rises.”
The FDF expects the resulting inflationary pressure to arrive later and persist for longer than previous shocks. Its latest forecast puts food and non-alcoholic drink inflation at 3.9% by December 2026, averaging 2.8% across 2026, before averaging 5.5% in 2027 and peaking at 6.4% in July 2027.
Energy and transport costs remain a significant contributor to inflation. Petrol rose 9.1p per litre in August to 161.3p, its highest level since November 2022, while diesel increased 14.2p to 181.8p. Motor fuel inflation reached 23.0% year-on-year, up from 15.5% in July, while electricity, gas and other fuels increased 0.9% during August and 6.0% year-on-year. These increases helped push headline CPI inflation to 3.1%, up from 2.9% in July.
Despite these pressures, consumer confidence continued to improve. The GfK Consumer Confidence Index rose four points between July and September, reaching its highest level since August 2024, as households became more optimistic about their personal finances and the wider economic outlook.
Outlook and Opportunities
With further cost increases expected, businesses should make sure they are getting as much value as possible from the money they are already spending. This includes:
- Tracking supplier rebates throughout the agreement, not just at year-end; being £5,000 short of a spend threshold could mean missing out on a £30,000 rebate.
- Looking beyond headline laundry prices; changes in stay patterns, linen specifications, reject rates and delivery discrepancies can all increase costs without the contracted price changing.
- Knowing your energy usage and key contract dates; reviewing options well in advance gives businesses more time to respond to market changes rather than trying to time them.
- Starting contract renewals early and benchmarking before negotiating; allowing agreements to roll over can mean missing the opportunity to challenge pricing, service levels and terms.
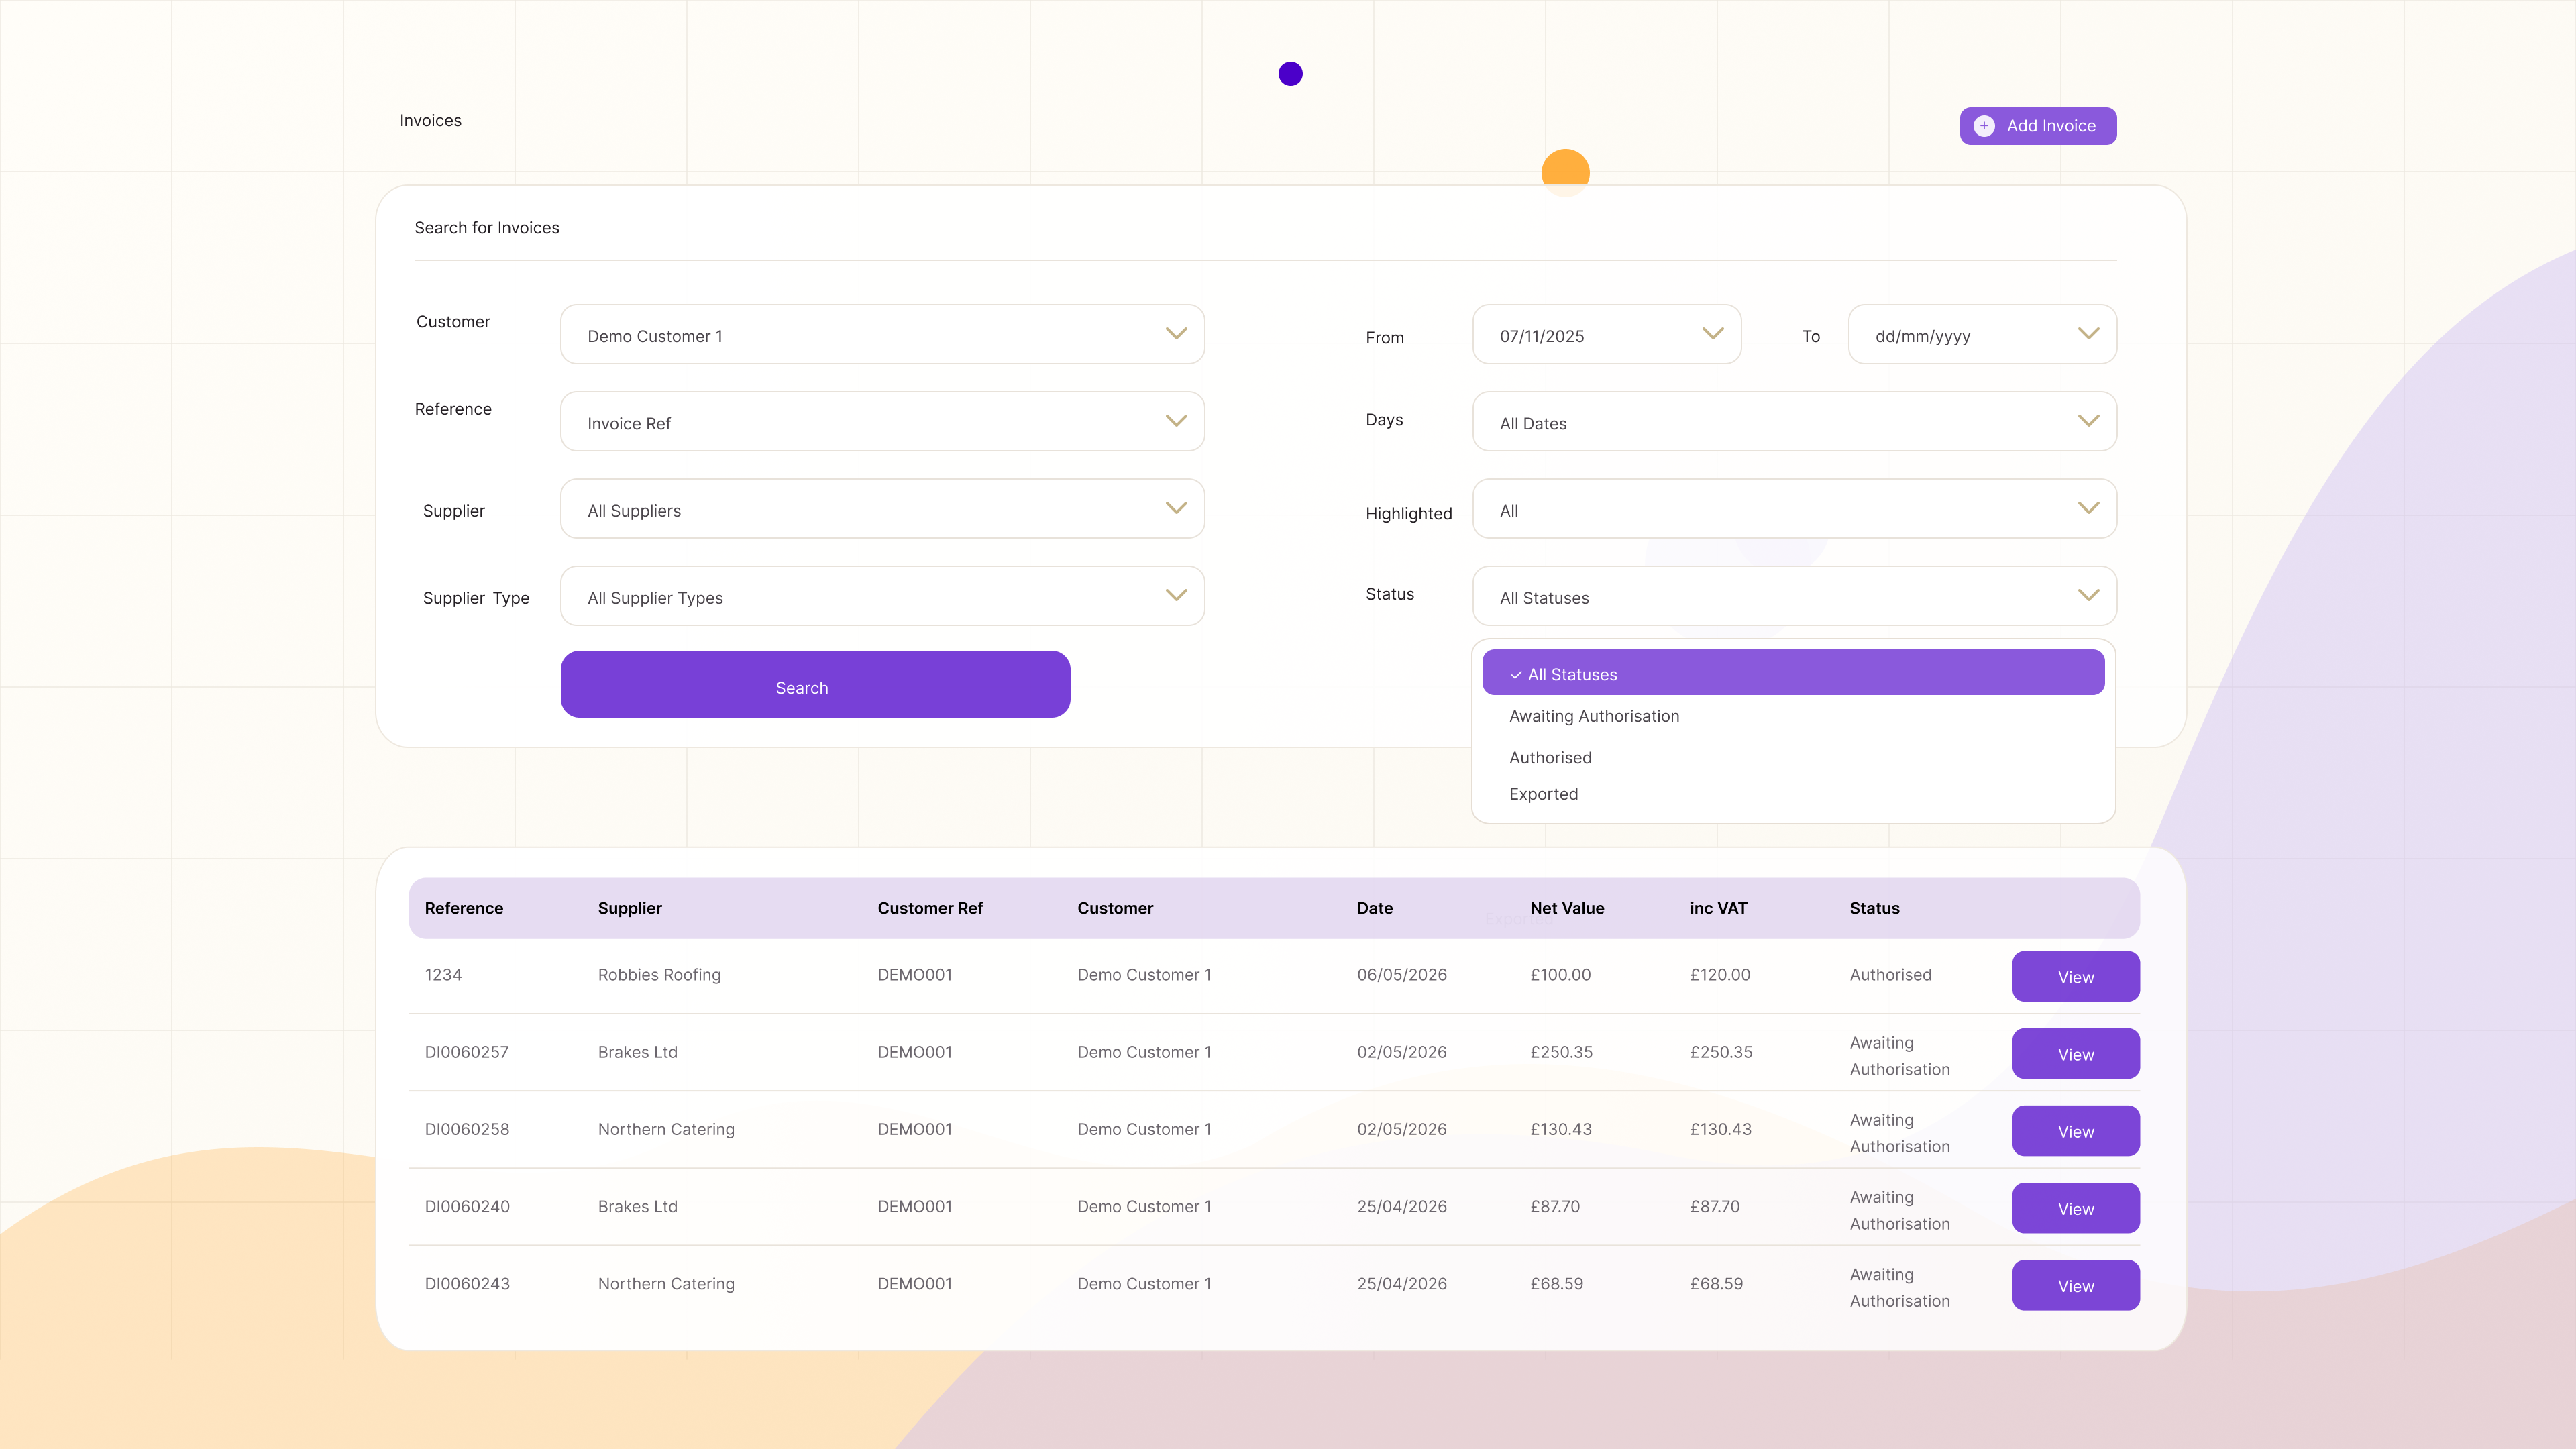
- Keeping a close eye on invoices; line-by-line data can identify price changes, overcharges and any unusual purchases.
To identify where your business could be getting more value from its spend, and the steps you can take to achieve it, book a call with our team.
AHDB (2026). August 2026 dairy market review
AHDB (2026). Final harvest report
AHDB (2026). Impact of heatwaves on dairy farms
Brakes (2026). Crop Reports: September
Food and Drink Federation (2026). UK food inflation forecast
Met Office (2026). Summer 2026 hottest on record
Office for National Statistics (2026). Consumer price inflation: September
UK Parliament (2026). Economic update